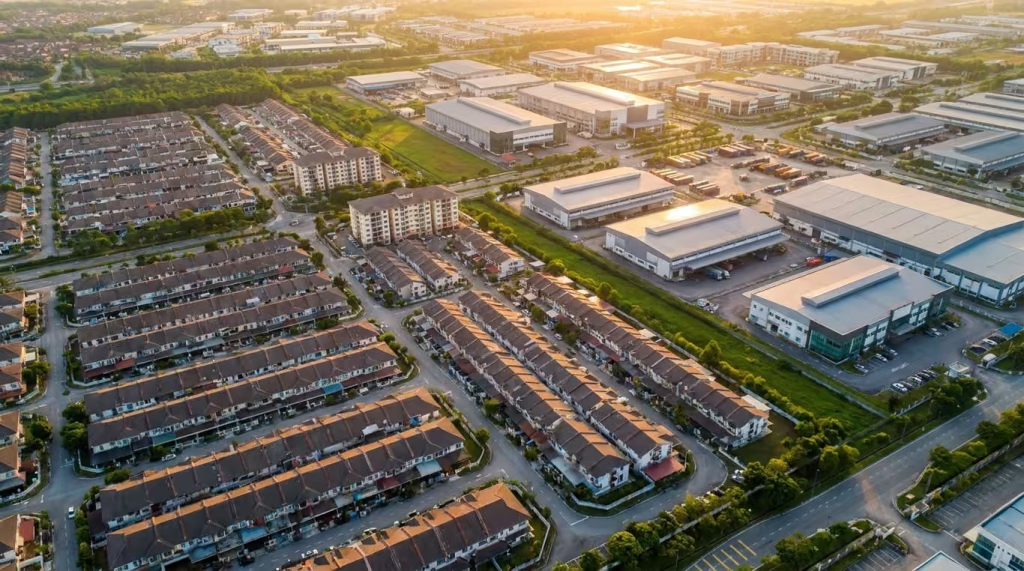
Malaysia’s residential property market is facing a growing overhang of completed homes, raising concerns that the widening gap between what developers are building and what Malaysians can afford or are willing to buy could worsen without targeted intervention.
A total of 33,094 completed residential units worth RM17.78 billion remained unsold in the first half of 2026, up from 30,471 units worth RM17.73 billion in the second half of 2025, according to the National Property Information Centre (NAPIC).
The increase is particularly concerning as unsold stock is no longer confined to high-end properties, with significant overhang also recorded in affordable and mid-priced segments.
Finance Minister II Amir Hamzah Azizan said at the launch of the 1H2026 Property Market Report on Sept 10 that the overhang was also heavily affecting the commercial segment, particularly serviced apartments.
The number of completed serviced apartments that remained unsold rose to 23,375 units worth RM19.33 billion. More than 55% of these units were priced between RM500,001 and RM1 million.
Calls for housing campaign as overhang grows
Real Estate and Housing Developers’ Association Malaysia (Rehda) president Zaini Yusoff said a special Home Ownership Campaign (HOC) 2027 should be introduced to help absorb existing completed residential units with a Certificate of Completion and Compliance.
He said a campaign similar to the HOC could improve market liquidity by helping clear completed stock and allowing developers to recycle capital into new projects.
However, Olive Tree Property Consultants founder and chief executive officer Samuel Tan said the problem went beyond a temporary mismatch that could be resolved simply by stimulating purchases.
He said several structural factors were contributing to the persistent gap between housing supply and effective demand.
‘Median household income has not kept pace with building costs, so the bulk of the new supply clusters above what first-time house buyers can afford, even as the RM300,000 and below segment is classified as affordable by price tag,’ he said.
Tan said financing remained another major obstacle, particularly for first-time buyers in the gig economy or those without fixed incomes.
He said difficulties in securing bank loans could prevent potential buyers from entering the market even when properties fell within their nominal price range.
‘Bank Negara’s loan rejection rates for first-time buyers, particularly gig-economy or non-fixed-income earners, remain a structural choke point the price alone cannot fix,’ he said.
Location, legacy stock and changing buyer preferences
The mismatch was also geographical, with overhang concentrated in particular states, locations and price segments.
Tan said some unsold stock comprised legacy developments planned during the 2012-2017 speculative cycle, including projects targeted at foreign and cross-border buyers whose demand did not materialise to the extent originally anticipated.
‘Overhang is heavily concentrated in specific states and price segments; much of it are legacy stocks from the 2012 to 2017 speculative wave aimed at foreign/cross-border buyers who never materialised to the expected extent,’ he said.
Tan said recent NAPIC data showed oversupply concentrated in high-rise properties, with unsold units increasingly common even in the RM200,000 to RM600,000 range.
This means location, layout and connectivity are now bigger drivers of unsold stock than price alone, he said.
Another concern is the long development cycle, which can leave developers delivering homes based on demand assumptions that are several years out of date.
Tan said approval-to-completion cycles could take three to four years, meaning homes being completed today might have been planned for a very different market.
‘The preferences and tastes of new buyers could have changed, rendering some of these unsold stocks unattractive,’ he said.
Strong transactions but persistent affordability gap
The issue is emerging despite an otherwise resilient property market.
The overall market recorded 187,320 transactions worth RM105.12 billion in the first half of 2026, while residential properties accounted for 59.3% of total transactions, with 110,998 deals, according to the 1H2026 Property Market Report.
The contrasting figures point to a more complex problem: transactions remain relatively strong, but a substantial pool of completed homes is still failing to find buyers.
Tan also highlighted a significant data gap that could hamper policymakers’ ability to address affordability, particularly among younger Malaysians and first-time buyers.
He said current data compiled by the Statistics Department was largely classified by income group and locality rather than age, making it difficult to establish how homeownership rates vary among different generations.
Without age demographics, stakeholders cannot distinguish between young people who cannot afford to buy and those who are choosing to rent or delay homeownership, he said.
He added that the absence of a baseline homeownership-by-age rate also makes it difficult to determine whether housing policies are narrowing the youth homeownership gap or merely helping to reduce existing property inventory.
Tan said this represented an important blind spot for housing policy, particularly as affordability pressures and changing preferences among younger buyers reshape demand.
On whether development approvals should be tightened to prevent further oversupply, he said supply controls and demand-side measures needed to be calibrated rather than applied as blanket national policies.
‘Tightening approvals can address the supply issue, but it does nothing to directly clear the existing overhang,’ he said.
A broad tightening could also risk creating shortages in genuinely undersupplied micro-markets, such as areas close to public transport and priority growth corridors.
On the demand side, measures such as financing guarantees, stamp duty exemptions and the RM20 billion credit guarantee scheme could help buyers access existing homes and accelerate the absorption of unsold stock.
But Tan cautioned that demand-side incentives could also allow developers to maintain prices that might otherwise need to adjust to clear mismatched inventory.
He said a more targeted approach would be to align policy intervention with specific segments and locations.
‘The more effective way, and one implicit in the government’s own framing, is targeting incentives at the segment level, such as stronger guarantees/financing support for the RM300,000 and below band, where genuine affordability is the constraint.
‘Pair this with strict approval discipline in the over-supplied high-rise category, and the entire mechanism will become more effective,’ he said.
The challenge for policymakers, therefore, is no longer simply how to get Malaysians to buy more homes, but how to ensure future housing supply is aligned with where people want to live, what they can afford and whether they can actually obtain financing.
Tan said that with completed unsold residential stock already exceeding RM17 billion, failure to address these structural mismatches could leave Malaysia with a cycle in which new supply continues to be added while existing homes accumulate as overhang.
National House Buyers Association (HBA) honorary secretary-general Chang Kim Loong previously told Business Times that homes priced below RM300,000 were traditionally viewed as the most accessible entry point for first-time buyers but were increasingly failing to translate into actual purchases.
He said the current overhang demonstrates that Malaysia faces not simply a ‘housing shortage’, but a shortage of well-located, financeable and genuinely affordable homes.


